By Honorine Uwishema, Senior Branch Manager at cPort Credit Union
What Is Credit?
Put simply, credit is when you borrow money now and agree to pay it back later. People often use credit to pay for important things like car repairs, school costs, or home repairs when they do not have enough money on hand.
If you have an expense you can’t afford,, a lender such as a bank or credit union may lend you the money. You then pay it back over time. Usually, you also pay a little extra on top of the amount you borrowed, which is called interest.
Before lending you money, a lender checks whether you are likely to pay it back. They may look at your income, job history, where you live, and your credit report.
Your credit report is a record of how you have used credit in the past. It shows what loans and credit cards you have used, if you paid bills on time, and if you missed payments. All of these factors combined help credit agencies (like TransUnion, Equifax, and Experian) determine your credit score.
What Is a Credit Score?
ADVERTISEMENT

A credit score is a number that shows lenders how likely you are to pay back money on time. In the United States, credit scores range from 300 to 850. A higher score will make it easier to get a loan or credit card. A higher score may also help you get a lower interest rate, so the total cost of your loan will be lower once you’ve paid it all back. Your score is based on the information in your credit report. Lenders get this information from one or more of the credit agencies..
Understanding Credit Scores
Different credit agencies use various scoring systems, meaning your exact score may vary slightly from one institution to another. However, using TransUnion’s VantageScore 3.0 model as a guide, you can generally understand what these numbers represent. A score falling between 300 and 600 is considered poor or poor, while a score from 601 to 660 is categorized as fair. Scores from 661 to 780 are considered good. Moving higher, a score between 781 and 850 is classified as excellent.
Factors That Affect Your Credit Score
While many factors impact your credit score, certain carry more weight than others. The most significant factors include your history of on-time payments, the amount of your available credit, how much of it you are currently using, and the overall length of your credit history. Consistently paying your bills on time is one of the best ways to build a higher score.
Similarly, using a smaller portion of your available credit is highly beneficial; in fact, many financial experts recommend keeping your credit utilization below 30% of your total card limit. Additionally, longevity matters, as someone who has actively managed credit for many years will typically have a higher score than someone who has only been using credit for a few months.
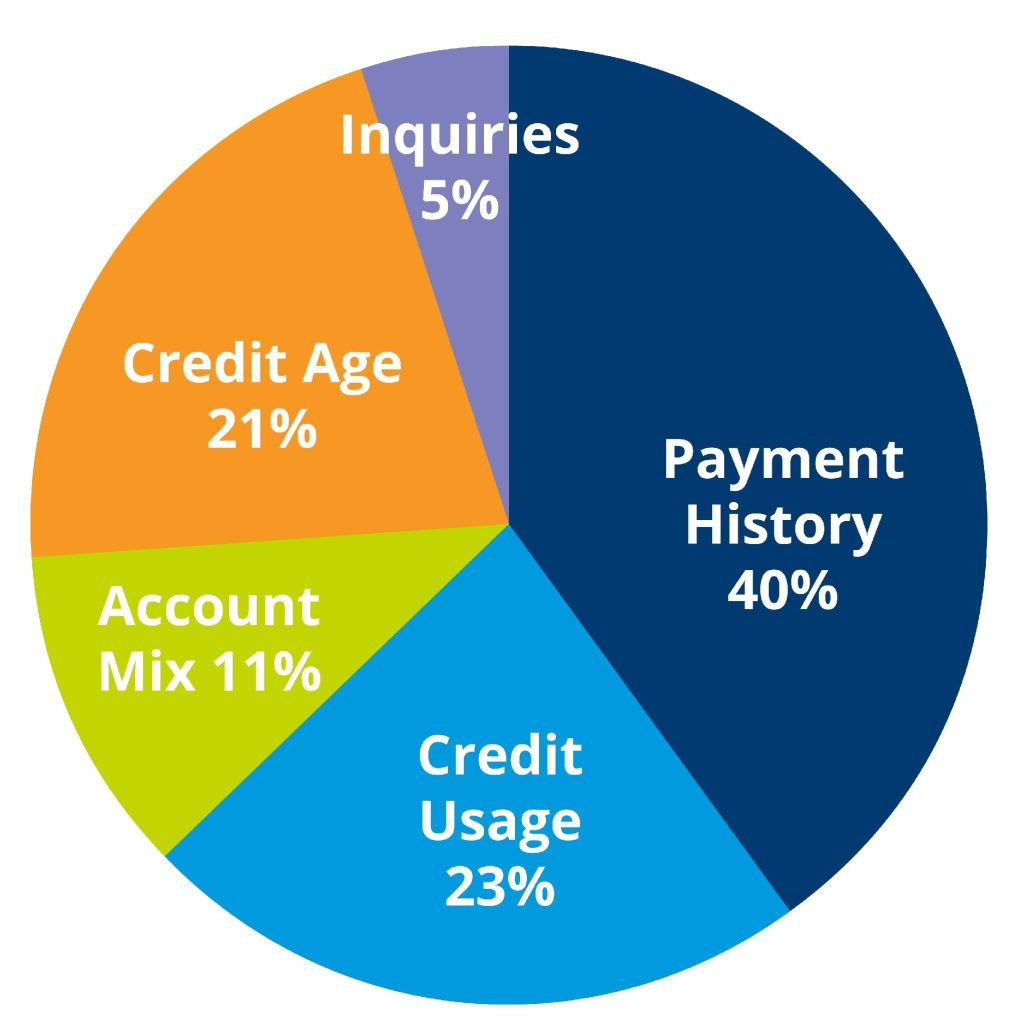
To summarize, there are five primary components that dictate your credit score: The first is your payment history, which simply tracks whether or not you pay your bills on time. The second component is your credit use, which measures exactly how much of your overall credit limit you are currently utilizing. Third, the length of your credit history (how long your credit accounts have been established and active). Fourth, it is important to be cautious with new credit, as opening several new accounts within a short period of time can actually lower your score. Finally, the types of credit you carry play a role, because having a diverse mix of accounts, such as managing both a revolving credit card and an installment loan, can positively impact your overall score.
This image shows how much each factor affects your credit score:
Why Does Good Credit Matter?
Good credit can make it easier and cheaper to borrow money. A higher credit score can help you get approved for a loan or credit card, especially when you want to buy large items like a car, furnace, or HVAC system. A higher credit score can also mean that you may pay less interest. Building credit takes time, but small steps can help.
How Do I Check My Credit Score?
Many banks and credit unions let their customers check their credit score for free. Ask your bank or credit union if they offer this service.
Federal law gives you the right to get one free credit report each year. You can request it online, by phone, or by mail. To learn more about checking your credit score, talk to your local bank or credit union.
Editor’s Note: This article originally appeared in the early July 2026 print edition of Amjambo Africa.