More than 150 years ago, as textile mills transformed Lewiston and attracted workers from across the world, community leaders recognized a problem that could prevent newcomers from establishing permanent roots: They needed access to financial services.
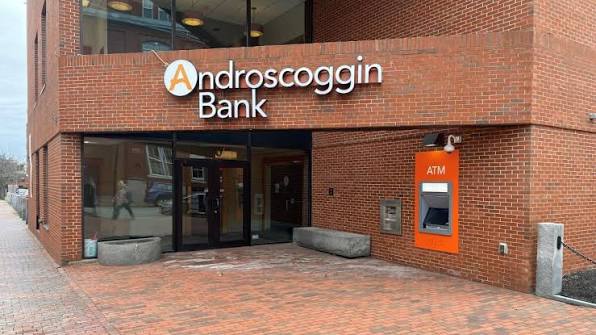
In 1870, community leaders established Androscoggin Bank in Lewiston to serve workers, including immigrants, arriving to work in the city’s mills. Today, the people coming to Maine are different, but the need for financial services that allow newcomers to build stable lives remains.
That history is now informing one of the bank’s newest initiatives: Rizq, a banking division focused on financial products designed to comply with Islamic principles.
For Neil Kiely, president and CEO of Androscoggin Bank, the connection between the institution’s origins and its work with Maine’s Muslim community is more than historical coincidence. “It’s in our DNA,” Kiely said in an exclusive interview with Amjambo Africa.
The bank’s story began when Lewiston was becoming one of New England’s important textile manufacturing centers. Kiely said the institution was formed to help workers who had come to the city, including immigrants.“Community leaders came together and formed our bank specifically to help people buy homes and then eventually start businesses,” Kiely said.
Today, Lewiston has once again become a city shaped by immigration. The French Canadian, Irish, and other European immigrants who helped build the city’s industrial economy have been joined by immigrants and refugees from Africa and other parts of the world. Lewiston and communities across Maine are now home to people from diverse backgrounds who bring new languages, cultures, religions, and economic needs to the state.
For Reza Jalali, the changes in Maine are exactly why financial institutions must continue to adapt. Jalali is the former executive director of the Greater Portland Immigrant Welcome Center. He came to Maine as a refugee in 1985 and has since advocated for immigrant integration, economic opportunity, and a sense of belonging.
While working with immigrants and refugees, Jalali repeatedly heard about one particular challenge: homeownership.
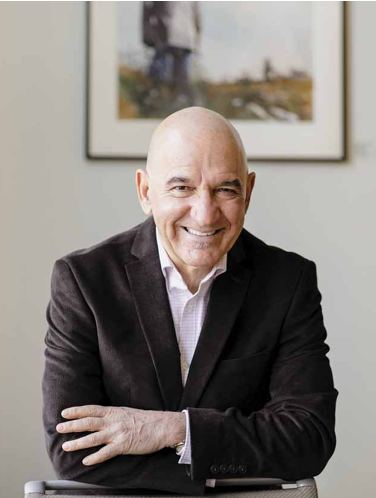
“When I was the executive director of the Greater Portland Immigrant Center, and before that, as an immigrant advocate, I was keen on identifying and addressing barriers that New Mainers were facing,” Jalali said. “The issue of homeownership, which represented establishing roots in Maine, kept coming up.”
For Muslim immigrants, the challenge was particularly difficult. Islamic financial principles prohibit the payment and receipt of conventional interest, known as riba. For practicing Muslims who follow that prohibition, a conventional mortgage can present a conflict between the desire to purchase a home and the requirements of their faith.
As Maine’s Muslim immigrant communities grew, Jalali said, what had once appeared to be an individual problem became a broader community issue.
A problem without a local solution
Before Rizq, Muslim families seeking to buy homes faced limited choices. Some delayed their plans. Some searched for lenders outside Maine. Others abandoned homeownership altogether.
Jalali has also heard of cases in which people became vulnerable to predatory lenders. “Prior to the initiative offered by Androscoggin Bank, community members were forced to give up their dream of homeownership, or shop for out-of-state lenders,” he said. “In some cases, [they] became targets for ‘loan sharks’ and signed fraudulent loan contracts with significantly higher interest rates.”
According to Jalali, the issue was not simply about finding a mortgage.
“Homeownership is also about belonging, establishing roots, and feeling safe and included,” he said.
Immigrants may spend years in transition before feeling settled enough to purchase a home. For some, buying a house represents a point at which they finally feel that they have arrived.
“Of course, it is also about generational wealth and ensuring a secure financial future for themselves and their offspring,” Jalali said.
The conversation begins
Jalali raised the issue with Kiely and began conversations with Androscoggin Bank about the unmet need.
But developing the product was not simply a matter of changing the language in a mortgage agreement. The bank had to understand Islamic financial principles while remaining within the requirements of U.S. banking law and regulations.
Kiely said the initial conversations began around 2022. “We did not set out specifically to do that,” Kiely said.
Instead, the bank had been examining how it could deepen its relationships with community partners as part of its commitment to becoming a Certified B Corporation and using business as a force for good. During that process, bank officials met with community leaders, including Jalali, as they worked to better understand the needs of Maine’s Muslim community.
“They explained to us the challenge that our Muslim neighbors were having because they could not use conventional bank products because they can’t pay or receive interest,” Kiely said. “And they asked us if we’d be willing to work on it with them.”
What followed was a lengthy process of research, consultation, and product development.Kiely said it took roughly 12 to 18 months to develop a workable solution. “It was challenging to reconcile the principles of the Islamic faith and Islamic financing with U.S. law and U.S. banking principles,” he said. The bank consulted Islamic finance experts and religious leaders and created a Sharia advisory board to review its products.
ADVERTISEMENT
The bank wanted to understand not only the technical requirements of Islamic finance but also the cultural expectations and concerns of the people who would eventually use the products. Kiely began visiting mosques and meeting with Muslim community members.
The bank also hired people from the Muslim community, including Mohammed Mohammed, whom Kiely described as a community ambassador.
The process reflects a philosophy that Kiely said is central to the bank’s identity: Community members should have a voice in shaping the solutions intended to serve them.
Listening and going back to the drawing board
Jalali said the bank listened to community members while also respecting the regulatory and legal requirements under which it operates. “Androscoggin Bank was willing to listen and evaluate the community’s needs while staying sensitive to state and federal regulations and the bank’s policies,” he said.
For Jalali, that willingness is part of what made the initiative possible. “Androscoggin Bank, as a Certified B Corporation bank, has been committed to uplifting the community by removing barriers to banking for every Mainer,” he said.
How Rizq works
Rizq is the name the bank has given to its Islamic banking initiative. Kiely explained that one of the central principles of Rizq is avoiding conventional interest. Under Islamic financial principles, the bank cannot simply charge interest on a conventional mortgage.
Instead, Androscoggin Bank developed a home-financing structure based on an installment sale. The prospective buyer identifies the home they want to purchase. The bank purchases the property and then sells it to the customer at a disclosed profit, with the customer making payments over time.
As Kiely explained, the structure is designed to comply with Islamic financial principles while providing an economic outcome comparable to conventional home financing.
Kiely emphasized that Rizq is not intended only for Muslims. “Anyone can use these products,” he said.
But for Muslim families who have been unable or unwilling to use conventional mortgages because of their religious beliefs, the significance is different. “There are some folks in the Muslim community who absolutely would not buy a home unless they can use it in an Islamic-compliant way,” Kiely said.
Trust is part of the product
For the bank, developing a compliant financial structure was only one part of the work. The other was trust.
Kiely said the bank recognizes that some Muslim families may be hesitant to place their financial affairs in the hands of an institution that was not historically part of their community.
“We have to be very conscious of making sure that everything we do brings us closer to trust with the community and humility,” he said. But he added that trust cannot simply be announced; it has to be earned.
“We understand that we have an obligation and a responsibility to earn their trust.”
Jalali said, “As an immigrant advocate, my role has been to identify unmet needs, be it in education, starting businesses, finding jobs, or becoming a homeowner, among others, and to bring the stakeholders together to find solutions that will help my fellow immigrants.”
His commitment comes partly from his own experience arriving in Maine as a refugee in 1985. “Other than Adult Ed, teaching English to immigrants in need of learning the language, there were no services to help refugees and immigrants integrate and feel belonged,” he said. Jalali believes Androscoggin Bank’s own history helps explain why it was willing to listen.
A bank’s old mission meets a changing Maine
Kiely said the bank’s mutual structure is central to how it views its responsibility.
“The concept of mutuality means we’re all connected and we all thrive,” Kiely said. “And to the extent that anyone is diminished in our midst, we’re all diminished.”
As Maine becomes more diverse, Jalali said, banks and other institutions must recognize that immigrants bring economic power as well as cultural diversity. “The newcomers have an enormous purchasing power,” he said. “Their presence in Maine has a significant economic impact.” Immigrants start businesses, buy homes, create jobs, and contribute to local economies.
However, immigrants’ financial needs are not always the same as those of people born in the United States. For Muslim immigrants, those differences can include the need for financial products that accommodate Islamic principles.
This need extends beyond homeownership, said Jalali.Muslim entrepreneurs may need business financing structured around their religious requirements. Families may need savings and investment products that similarly accommodate their beliefs. His hope is that Rizq eventually develops into a broader range of services.
Kiely said the bank has also heard from communities outside Maine interested in similar services, including people in New Hampshire and Massachusetts. But the bank wants to deepen its work in Maine before expanding.
“We want to focus first on the Maine community,” Kiely said, “because we do have that ability to be intimate and to learn from Muslim neighbors about what they need, what they want, and how they want it.”
The meaning of a home
The impact of Rizq is perhaps easiest to understand through the families who have used it.
Kiely recalled the first Muslim family the bank helped purchase a home. After the purchase, the family invited bank representatives to an open house. The children took the visitors by the hand and showed them their rooms. “The pride in their eyes and the pride in this couple’s eyes about having their own home and the family, the children have their own rooms,” Kiely said.
The meaning is similar for JalaliHe recalled visiting a family that had previously lived in a small apartment where the children had to share rooms. After buying a home, the family had enough space for everyone.
“Their youngest child gave me a tour of the new home, with a smile that brightened the room,” Jalali said.
Those moments illustrate why Jalali sees homeownership as more than a financial transaction. Owning a home can give immigrants a stronger sense of belonging and a stake in the community.
“Once an immigrant becomes a homeowner, they feel ownership in the community where they live,” he said. “They are more likely to vote, volunteer, run for office, and so on. They become a stakeholder.”
More than a business opportunity
Kiely said the bank views Rizq as both a business opportunity and a community initiative. The bank’s mutual structure influences that philosophy.
“It is good to do philanthropy,” Kiely said. “It is better if you can make it part of your business so that as your business thrives and grows, you can do more.”
“If we can make more profit, it just goes back in,” he added.
Five years from now, Kiely said, success would mean having a thriving Rizq division offering a broader range of Islamic-compliant financial products.
He envisions Muslim customers being able to obtain the same kinds of financial services available through conventional banking while having structures that align with their religious principles.
“Adding a chair or two”
For Jalali, Rizq represents something larger than banking. He sees it as evidence that Maine is changing.
“There was a time when Maine was ‘tolerating’ those born outside of the U.S.,” he said. “But we as a state are evolving and are accepting our new neighbors.”
He described the Rizq initiative in simple terms: “This initiative is about adding a chair or two to welcome our new neighbors and make them sit at the table.”
Diversity reinforces the bank’s original mission, according to Kiali.“We see the immigrant community here as the future of Maine,” he said.
The willingness of a longstanding Maine institution to adapt its practices to meet the needs of new Mainers represents a meaningful sign of inclusion to Jalali.
“I am proud of living and being part of a community that is willing to adjust their business practices and offer new initiatives to make us, as newcomers, feel at home,” he said.
For Eric Nyamunanira, a Muslim from Rwanda who lives in Lewiston, the opportunity represented by Rizq carries a deeply personal meaning. “It is an opportunity you rarely find outside Muslim-majority countries, including those in the Arab world. For me, it is like a dream come true,” Nyamunanira said.
For some Muslim families, that feeling of home may begin with a key turning in the lock of a house they can finally call their own.